

HRBT Faces Weekend Lane Closures for October Repaving Work
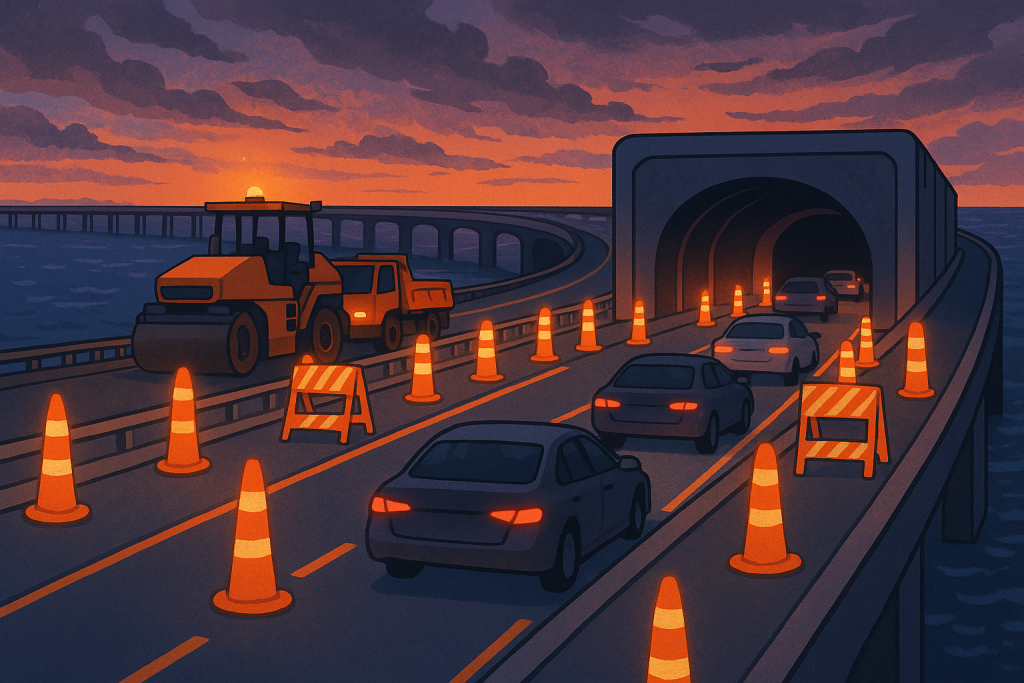
The Virginia Department of Transportation plans to fully close the Hampton Roads Bridge-Tunnel one direction at a time across several October weekends to allow for repaving.
Vinyl Window Warranty Coverage: What Homeowners Need to Know
Vinyl window warranty coverage is one of the most important and most consistently misunderstood aspects of a window replacement purchase — and the gap between what homeowners assume a warranty covers and what it actually covers frequently only becomes apparent when something goes wrong and a claim is filed. Understanding what quality window warranties actually include, what the common exclusions are, and how to compare warranties across manufacturers before committing to a purchase is what allows homeowners to make informed decisions rather than discovering the limitations of their coverage at the worst possible moment. What Lifetime Warranties Actually Mean The term "lifetime warranty" appears across a wide range of vinyl window products at very different price points — which should immediately raise the question of what lifetime means in this context and what it actually covers. In the window industry lifetime warranties are typically limited lifetime warranties that define lifetime as the original purchaser’s ownership of the home rather than the actual lifespan of the product, which is a meaningful distinction that affects transferability and long-term value. A warranty that is tied to the original purchaser doesn’t transfer to a subsequent buyer — which means the home’s next owner has no warranty coverage on windows that may still have decades of useful life remaining. For homeowners who plan to sell within the warranty period, this transferability question directly affects what the warranty is actually worth as a purchase consideration. Some manufacturers offer fully transferable warranties or warranties that transfer with a reduced coverage period — which is a genuinely meaningful differentiator that deserves attention during the comparison process. Glass Unit Coverage and Seal Failure The most commonly claimed warranty item in vinyl windows is seal failure in the insulated glass unit — the fogging or hazing that appears between panes when the seal around the gas-filled space fails and allows moisture infiltration. Quality window manufacturers cover seal failure explicitly in their glass unit warranty, typically for the lifetime of the original owner or for a defined period. The specific coverage — whether the manufacturer covers the glass unit replacement only or also covers the labor to remove and reinstall the affected window — varies significantly and affects the real cost of a warranty claim. Energy efficient vinyl windows with quality glass unit construction and robust sealing have lower seal failure rates than lower-quality alternatives — but understanding the warranty coverage for seal failure before purchase rather than after it occurs is what ensures that when it does happen the coverage is what the homeowner expected. Frame and Hardware Coverage The vinyl frame itself — the extrusions that form the window’s structural perimeter — typically carries longer warranty coverage than other components because vinyl is inherently durable and frame failure is relatively rare in quality products. What’s more variable is coverage for hardware components — the locking mechanisms, hinges on casement windows, balances in double hung windows, and the operational hardware that gets daily use and has finite service life regardless of overall window quality. Hardware coverage that’s limited to a shorter period than frame coverage reflects the reality that operational components wear out sooner than structural ones — but the specific coverage period and whether it includes labor for hardware replacement are details worth confirming before purchase rather than assumptions to make. What Warranties Don’t Cover The exclusions in vinyl window warranties are as important as the coverage provisions — and they’re where the most significant surprises occur when claims are filed. Damage from improper installation is one of the most consequential exclusions — which is why contractor selection matters alongside product selection. A manufacturing defect is covered; damage that resulted from how the window was installed is not, and distinguishing between the two can become contested when a claim is filed. Damage from extreme weather events, improper cleaning or maintenance, and alterations to the window after installation are standard exclusions across most manufacturers. For vinyl replacement windows in coastal or high-humidity environments, understanding whether the warranty addresses any performance limitations related to those specific conditions is worth confirming before purchase. Using Warranty as a Quality Indicator Beyond its direct value as coverage, a manufacturer’s warranty terms are a meaningful signal of their confidence in their product’s performance and their commitment to standing behind it. A manufacturer offering robust coverage — full glass unit replacement including labor, transferable lifetime frame warranty, meaningful hardware coverage — is communicating something about how their product performs in the field that a manufacturer offering narrow coverage with extensive exclusions is also communicating, just in the opposite direction. The where to buy resource connects homeowners with dealers who can walk through warranty terms in detail for the specific products being considered — making the warranty comparison part of the purchase evaluation rather than an afterthought.
LG to Build $64M HVAC Plant in Isle of Wight County

LG Electronics plans a nearly $64 million assembly facility in Isle of Wight County that will produce HVAC equipment, including chillers aimed at the booming data center market.
Weather Damaged Car Trade In Options for Virginia Drivers

Weather damaged car trade in options Virginia drivers have after a flood, hailstorm, or other severe weather event are more accessible than most people realize — and more worth exploring than the default assumption that the insurance process is the only path forward. Virginia’s geography puts drivers in the path of significant weather events — coastal flooding, ice storms, severe thunderstorms with damaging hail, and the occasional hurricane remnant that pushes flooding well inland — and the vehicle damage those events produce creates exactly the kind of complicated situation where understanding all available options makes a meaningful financial difference. How Weather Damage Differs From Accident Damage Weather-related vehicle damage operates under a different set of insurance and liability dynamics than collision damage — and those differences affect what options are available and how the trade path fits into the overall picture. Collision damage involves fault determination, third-party liability, and the possibility of recovery from another driver’s insurer. Weather damage is a comprehensive insurance claim — it’s covered by the comprehensive portion of an auto insurance policy rather than collision coverage, which means the driver’s own insurer handles it regardless of fault because weather events don’t involve fault. The practical implication is that weather damage claims go entirely through the driver’s own comprehensive coverage — which means the deductible applies, the claim affects the driver’s own loss history, and the settlement offer comes from an insurer the driver has a direct relationship with rather than an adversarial one with a third party’s insurer. For drivers with higher deductibles or concerns about claim impact on future premiums, understanding the trade option alongside the insurance path is particularly valuable. Flood Damage and Why It’s Particularly Complicated Flood damage is among the most complicated vehicle damage scenarios because water intrusion into a vehicle’s electrical and mechanical systems creates problems that aren’t always immediately apparent and that can continue developing for weeks after the initial event. A vehicle that starts and drives after a flood event may have sustained damage to control modules, wiring harnesses, and mechanical components that will produce failures as moisture works its way through systems that weren’t immediately affected. This delayed damage progression is what makes flood vehicles particularly difficult to value accurately and particularly risky to repair — a repair estimate based on visible damage at the time of assessment frequently underestimates the total cost of restoring a flood-damaged vehicle to reliable operation because the full extent of damage hasn’t yet manifested. Insurance companies are aware of this and often total flood-damaged vehicles that might appear repairable based on visible damage alone. For drivers whose flood-damaged vehicles are declared total losses, the wrecked car trade in process offers an alternative to the insurance settlement timeline — trading on pre-flood value rather than accepting whatever the insurer’s total loss valuation produces. For vehicles that aren’t totaled but whose owners don’t want to deal with the uncertainty of flood damage repair, trading before submitting an insurance claim is an option worth evaluating. Hail Damage and the Repair vs Trade Calculation Hail damage presents a different cost-benefit calculation than flood damage because it’s typically cosmetic rather than mechanical — dents and paint damage rather than system compromise. A hailstorm that produces extensive roof, hood, and trunk damage can generate repair estimates that approach or exceed a vehicle’s value even when the car drives perfectly, which puts the repair vs trade decision in exactly the same territory as other total loss situations. Paintless dent repair — the technique used for hail damage that doesn’t break the paint surface — is effective for moderate hail damage but becomes uneconomical for extensive coverage that requires traditional body work and paint. A repair estimate in the four to eight thousand dollar range on a vehicle worth ten to fifteen thousand puts the driver in the position of spending significant money to restore a car to pre-storm condition when trading on pre-storm value and applying that toward a replacement might produce a better financial outcome. The trade my car in Virginia process establishes pre-storm trade value through an inspection that documents the vehicle’s condition and market value as it existed before the weather event — which is the figure that determines whether the trade path produces a better outcome than the repair or insurance settlement path. Timing After a Weather Event The timing of decisions after a weather damage event matters more than most drivers appreciate. Insurance claims have reporting requirements that vary by policy but generally require prompt notification. Trade decisions made before an insurance claim is submitted preserve more flexibility than those made after the claim process is already underway. And the market for replacement vehicles — and the availability of specific makes and models the driver might want — can shift in the aftermath of major regional weather events when many drivers are simultaneously seeking replacements. For Virginia drivers in the Roanoke and Richmond areas dealing with weather-damaged vehicles, getting a Roanoke wrecked car trade in evaluation quickly after a storm event — before committing to an insurance path or a repair path — provides the information needed to make an informed decision rather than one made by default.
Study: Nearly Half of Hampton Roads Homes Struggle to Afford Food
A new study finds that a large share of Hampton Roads households — and more than half of families with children — are struggling to afford enough food.
ITALY, ECOMONDO 2026: CIRCULAR ECONOMY DRIVEN BY INNOVATION AND INTERNATIONAL COOPERATION

RIMINI, Italy, Oct. 1, 2026 /PRNewswire/ — Ecomondo 2026, the international event organised by Italian Exhibition Group (IEG) and dedicated to the circular and regenerative economy, will return to Rimini Expo Centre from 3 to 6 November for its…
AeroCore Technologies Opens Middle East Headquarters in Riyadh, Saudi Arabia

Patented one-hour foam wash technology, delivered at the gate, will bring measurable performance, availability and fuel efficiency benefits to operators across Saudi Arabia and the GCC. RIYADH, Saudi Arabia, Oct. 1, 2026 /PRNewswire/ — AeroCore Technologies, inventor of Nucleated…
Threekit Launches AI-Native CPQ for Manufacturing: Built for the Web, Built for Dealers, Built for the AI Age

From the team behind BigMachines (now Oracle CPQ) and SteelBrick (now Salesforce CPQ), a new approach to CPQ that lets reps, dealers, customers and websites quote complex products as easily as having a conversation.CHICAGO, Oct. 1, 2026 /PRNewswire/…
KIA AMERICA POSTS BEST SEPTEMBER AND BEST QUARTERLY SALES TOTALS IN COMPANY HISTORY

September sales totaled 77,009 units and third-quarter sales reached 236,659 units, up 18 and 8 percent year-over-year, respectively, achieving record September and record quarterly salesRetail sales increased 19 and 9 percent year-over-year, reaching 70,429 units in September and…
ICEYE and Nokia partner to launch secure and sovereign satellite communications for governments and defense customers

Sovereign, dual-use satellite communications systems owned and operated by the nations that use them.HELSINKI, Oct. 1, 2026 /PRNewswire/ — ICEYE, the European leader in sovereign intelligence from space, and Nokia, a global leader in connectivity infrastructure, today announced…